Home Equity Line of Credit
Flexible revolving access to available equity for ongoing needs, projects, or liquidity planning.
SPECIALTY PROGRAM
Access available home equity without automatically replacing your existing first mortgage.
Featured Video
A focused video overview will be added here when the approved production is ready.
Equity Options
Second mortgage options can support different goals depending on available equity, payment preference, occupancy, and the full financing picture.
Flexible revolving access to available equity for ongoing needs, projects, or liquidity planning.
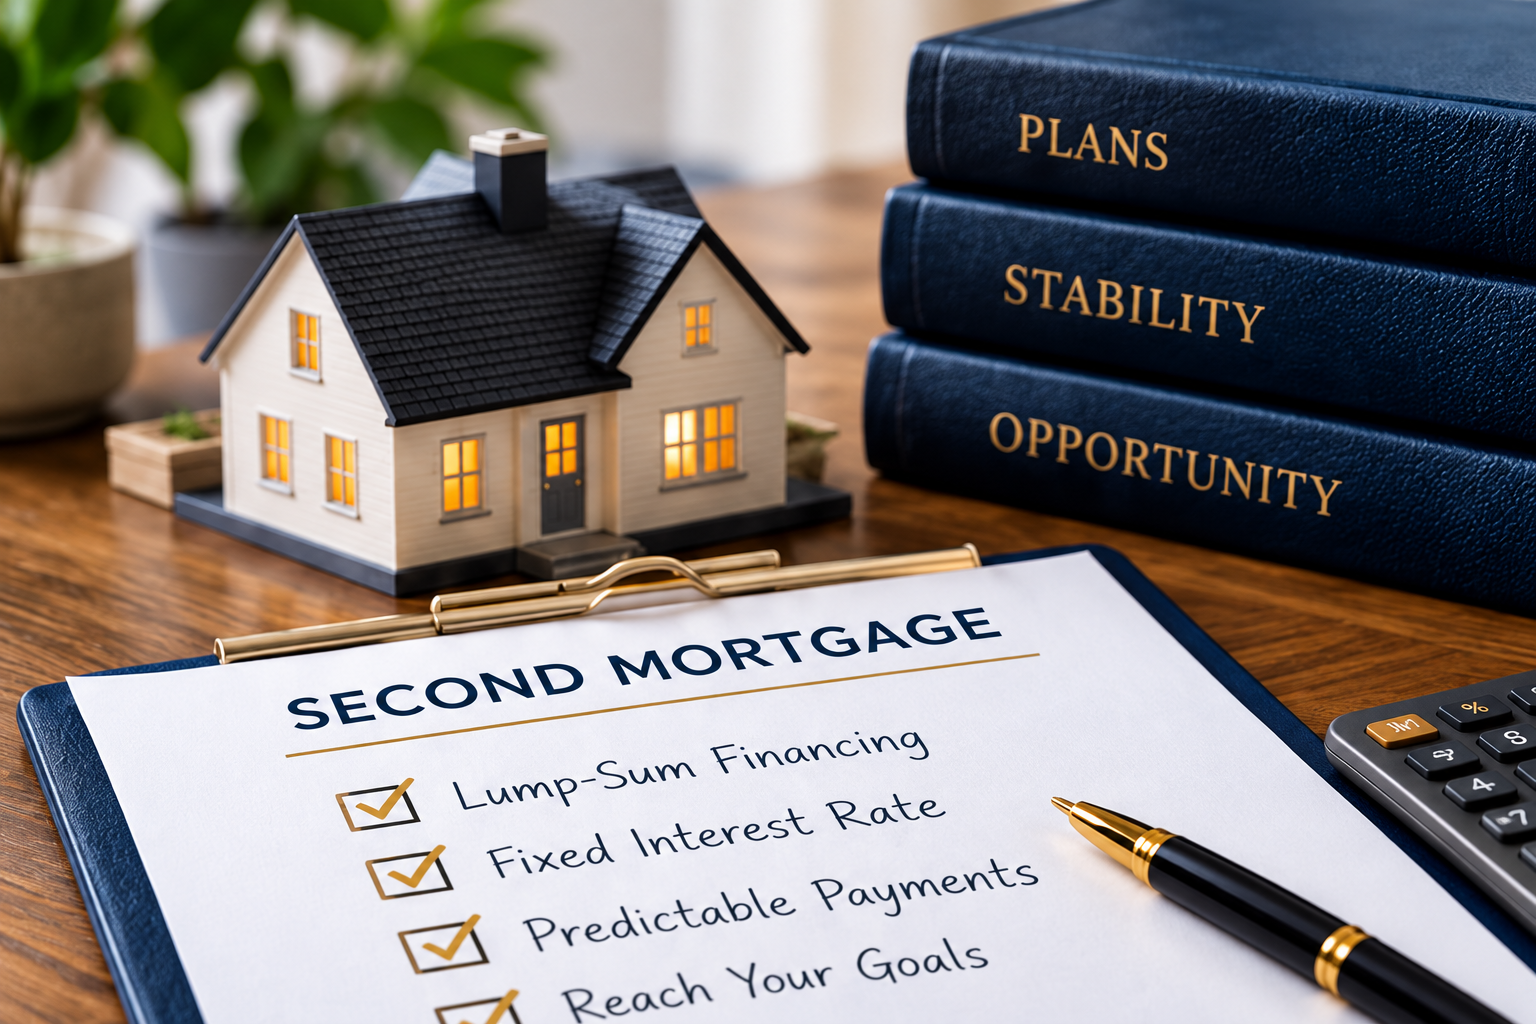
Receive a lump sum with predictable payments and a fixed rate while keeping the first mortgage in place.
Combine first and second financing to support the purchase structure and overall cash-to-close strategy.
Use available equity for renovation, upgrades, repairs, or property-improvement goals.
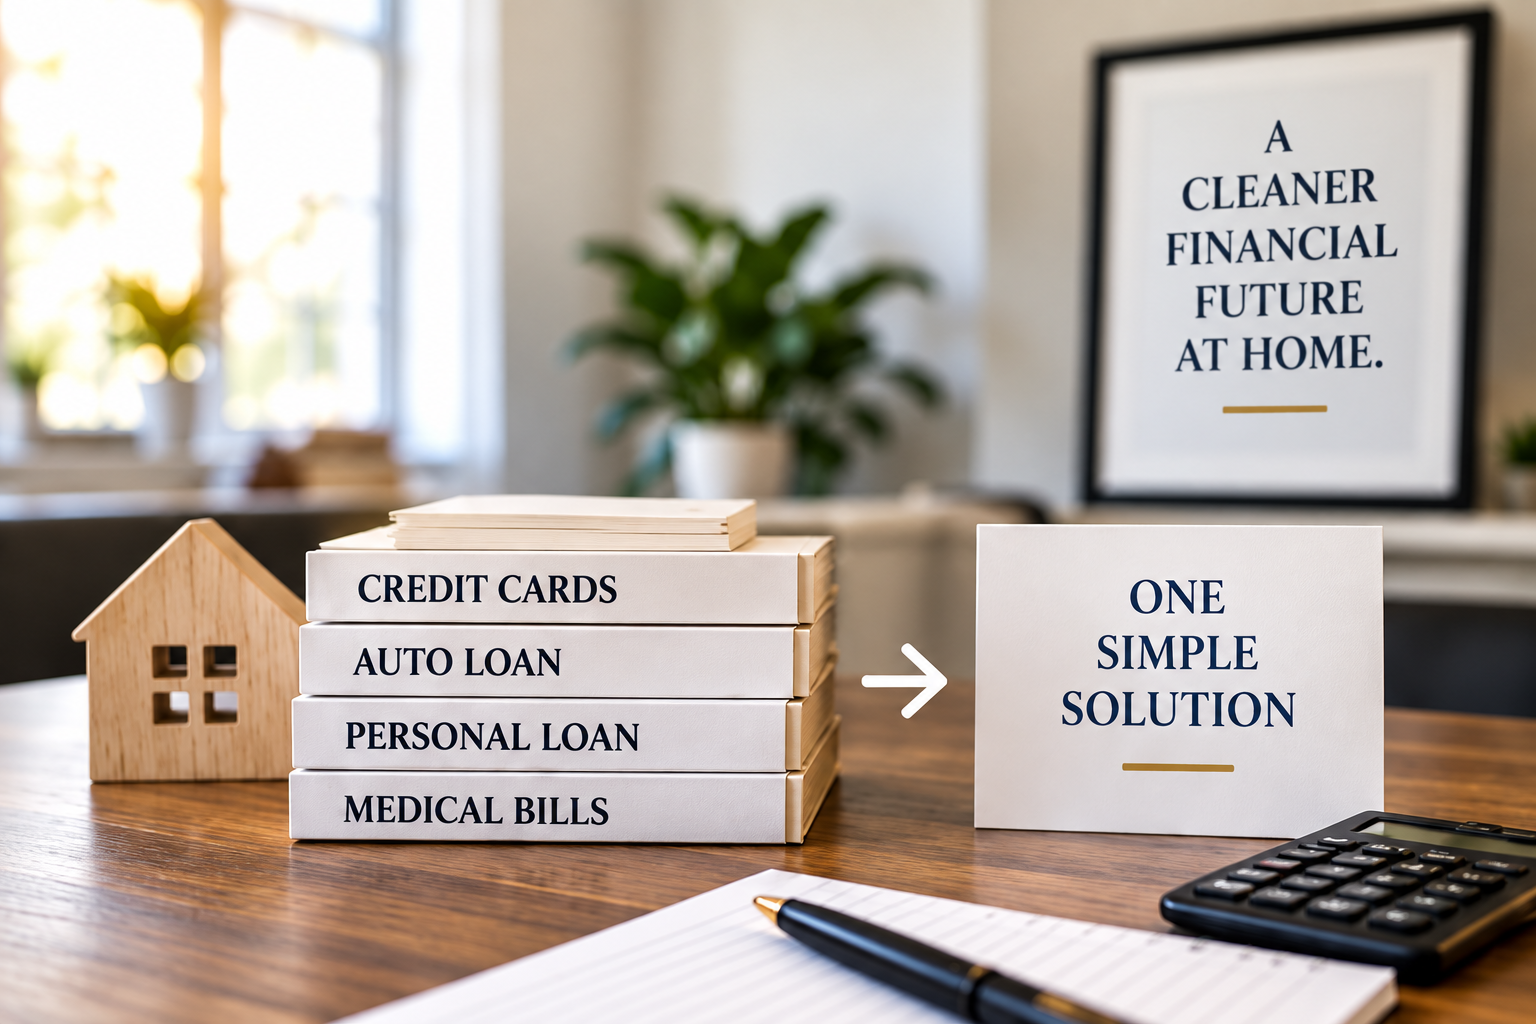
Consolidate higher-interest debt into one broader financing strategy when the full scenario supports it.
Explore ways available equity may support investment-property goals, portfolio moves, or future opportunities where permitted.
Program Snapshot
Review the core considerations that may shape a second mortgage or HELOC. Final eligibility, structure, terms, and availability depend on the complete application, property, transaction, and lender guidelines.
Available proceeds are based on the property value, current first-mortgage balance, requested second mortgage, and the program’s maximum combined loan-to-value limit.
Qualifying credit requirements depend on the product, occupancy, property type, loan amount, and overall borrower profile.
Income, employment, assets, liabilities, and the ability to repay must generally be documented. Available options may include traditional and alternative-documentation programs where eligible.
HELOCs may have separate draw and repayment periods, while fixed-rate second mortgages generally begin scheduled principal-and-interest repayment after closing.
An eligible second mortgage may be combined with a first mortgage to help structure the down payment, financing, or total cash needed to close.
Required borrower funds, down payment, reserves, and gift-fund eligibility depend on the first mortgage, second mortgage, occupancy, property type, and complete transaction structure.
An appraisal, automated valuation, or another acceptable property-valuation method may be required depending on the product and transaction.
Program guidelines, rates, terms, loan limits, credit requirements, combined loan-to-value limits, and availability may change. This information is educational and is not a commitment to lend or a guarantee of approval.
Frequently Asked Questions
A HELOC generally provides revolving access during a draw period, while a fixed second mortgage generally provides one lump sum with a defined repayment structure. Rates, payments, and terms vary by program.
Home improvements are a common potential use of second-mortgage proceeds. The property, available equity, borrower profile, and proposed structure must still meet current guidelines.
It may be considered as part of a broader debt-consolidation strategy. Compare total costs, payments, repayment period, and the risk of securing debt with your home before deciding.
Some programs may allow eligible investment properties. Availability depends on equity, occupancy, property type, borrower qualifications, and current lender rules.
Typically, no. A second mortgage is a separate lien behind the first mortgage, allowing the existing first mortgage to remain in place when the transaction is eligible.
Available equity starts with the property value and existing lien balances. The accessible amount also depends on combined loan-to-value limits, credit, income, occupancy, property type, and program guidelines.
Your Next Step
Share the property, current financing, available equity, and your goal so we can identify the paths worth a closer look.