Lower-Down-Payment Purchase
Eligible borrowers may purchase a primary residence with FHA financing and the required minimum investment.
FHA financing offers eligible homebuyers flexible qualification options, lower-down-payment opportunities, and financing solutions for primary residences, including certain multi-unit, manufactured-home, and renovation scenarios.
FHA Education
FHA Financing Paths
FHA financing may support eligible primary-residence buyers through several purchase, refinance, multi-unit, manufactured-home, and renovation strategies.
Eligible borrowers may purchase a primary residence with FHA financing and the required minimum investment.
FHA underwriting may provide options for borrowers whose credit profile does not fit conventional financing.
Eligible gift funds and approved assistance may help with the required investment or closing costs.
Eligible borrowers may purchase a two- to four-unit property when they will occupy one unit and satisfy applicable requirements.
FHA financing may be available for qualifying manufactured homes that meet property, foundation, title, and appraisal standards.
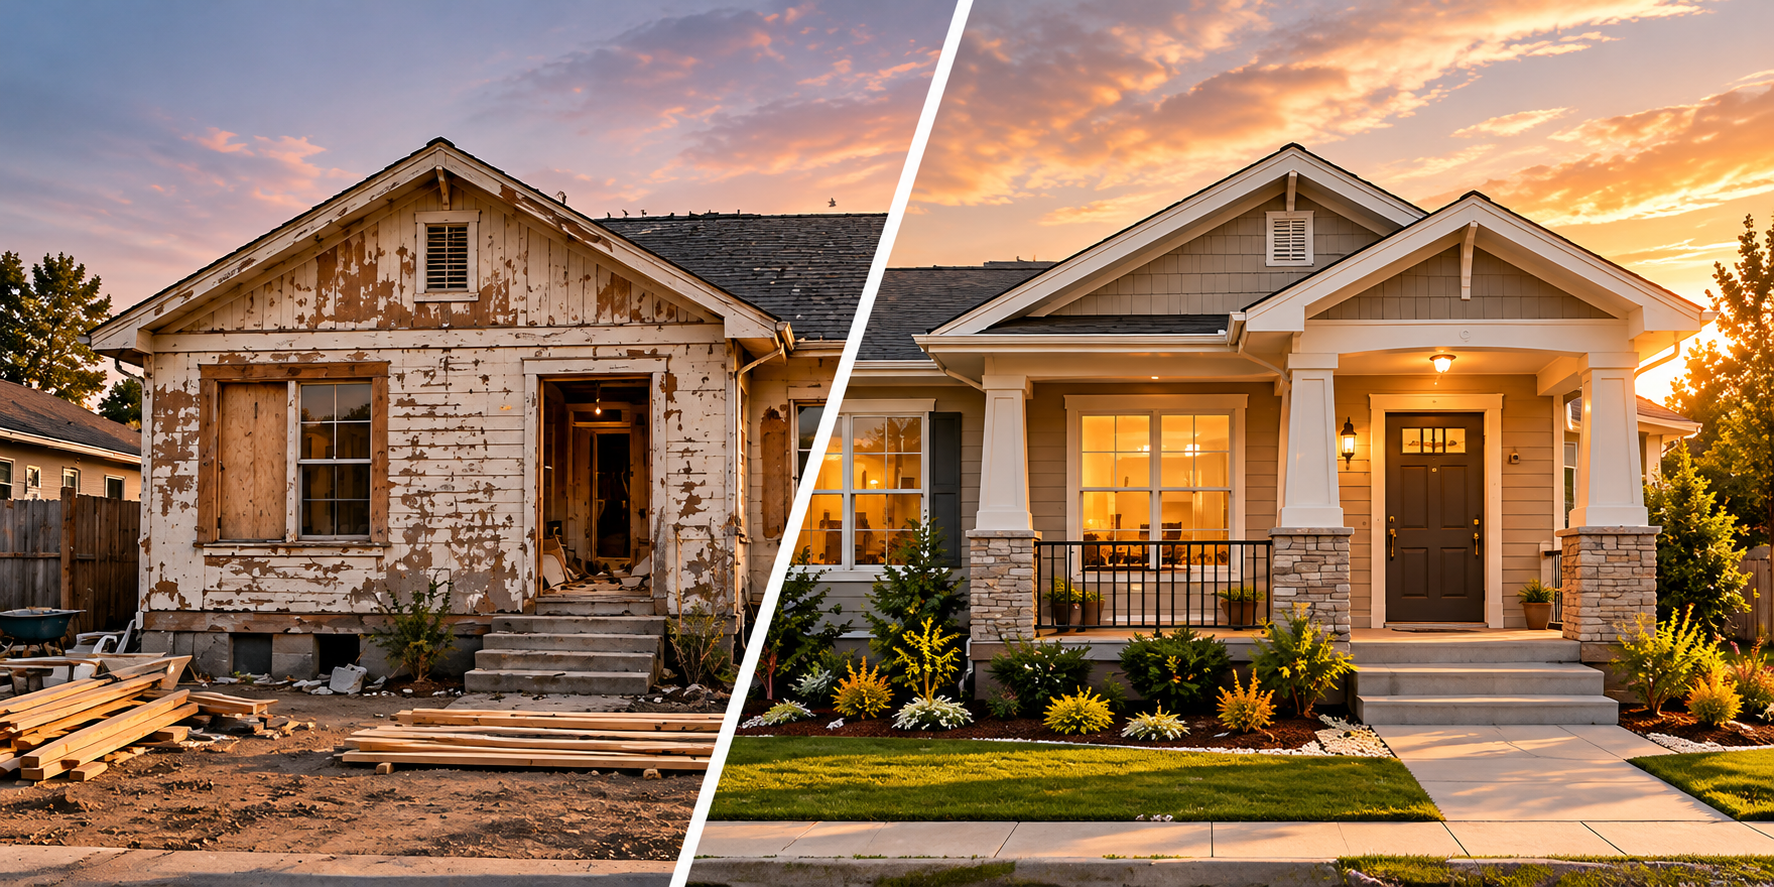
Eligible purchase or refinance transactions may combine FHA financing with approved renovation costs.
Program Details
Use these concise checkpoints as a starting point. Final eligibility, structure, terms, and availability depend on the complete application, property, transaction, and current program requirements.
Minimum Investment
Required borrower funds depend on the transaction and current FHA requirements; eligible sources may include gifts or assistance.
Credit Profile
The complete credit history and borrower profile are reviewed under current FHA and lender requirements.
Occupancy
FHA financing generally requires the property to be the borrower’s primary residence.
Property Types
Eligible one- to four-unit homes, approved condominiums, and manufactured homes may be considered.
Mortgage Insurance
FHA financing includes upfront and annual mortgage-insurance components under current program rules.
Gift Funds
Eligible gifts may be used when the donor, source, transfer, and supporting documentation meet requirements.
Seller Contributions
Permitted contributions are subject to current FHA definitions, transaction limits, and eligible closing costs.
Income & Employment
Stable, verifiable income and employment or other acceptable income sources must support repayment.
Debt-to-Income Review
Total obligations, income, compensating factors, and the complete application are evaluated together.
Appraisal & Property Standards
An FHA appraisal reviews value and minimum property standards; it is not a home inspection.
Loan Purpose
Eligible uses may include purchase, refinance, and qualifying renovation financing.
FHA Loan Limits
Applicable limits depend on the county, unit count, calendar year, and current HUD requirements.
Program guidelines, rates, terms, loan limits, credit requirements, property requirements, and availability may change. This information is educational and is not a commitment to lend or a guarantee of approval.
Questions
It is a mortgage insured by the Federal Housing Administration and originated by an approved lender.
No. Eligible repeat buyers may also use FHA financing.
The required investment depends on current FHA rules, credit qualifications, and the full scenario.
FHA loans generally include upfront and annual mortgage-insurance charges. Duration and cost depend on the transaction.
Eligible gift funds may be used when the source and transfer meet current documentation rules.
Eligible owner-occupied properties with up to four units may qualify, subject to program requirements.
For certain three- and four-unit properties, projected rents must satisfy a specific relationship to the proposed housing payment.
Your Next Step
Let's review your goals, explore your options, and build a financing strategy around your situation.
Experience • Guidance • Trust