Bank Statement
Eligible self-employed borrowers may qualify using an analysis of business or personal bank deposits.
Alternative financing solutions for borrowers whose income, property, or financial profile may not fit traditional mortgage guidelines.
A concise starting point. Final eligibility, terms, and availability depend on the complete application and current guidelines.
Eligible self-employed borrowers may qualify using an analysis of business or personal bank deposits.
Eligible investment-property scenarios may qualify primarily through property cash flow rather than personal income.
Qualified assets may be analyzed as a potential income source under specific program rules.
Eligible independent contractors may have options based on documented 1099 earnings.
Options may exist when supported by the available lender program and the full borrower profile.
Some programs may use a qualifying profit-and-loss statement with required verification.
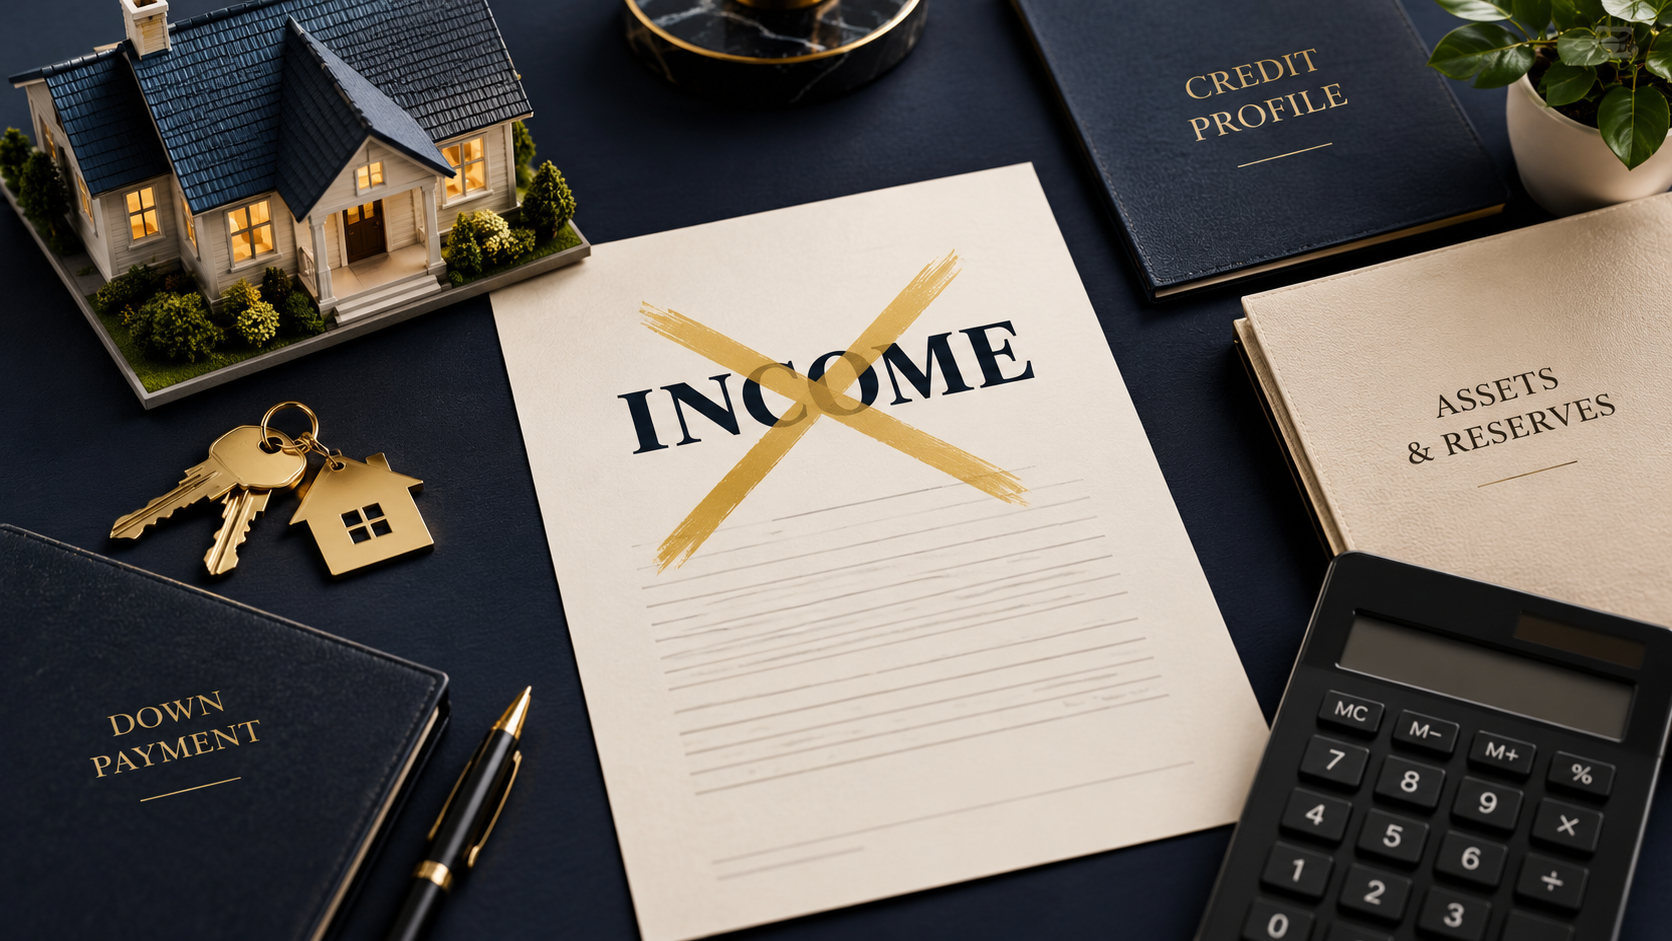
Eligible No Ratio programs may qualify borrowers without calculating a traditional debt-to-income ratio. Credit, assets, down payment, reserves, property type, and other program requirements still apply.
Options may be available after bankruptcy, foreclosure, short sale, or another significant credit event. Required seasoning, re-established credit, equity, reserves, and other guidelines vary by program.
Program Details
These are general starting points. Final eligibility, terms, and availability depend on the complete application, property, transaction, and current lender guidelines.
Down Payment or Equity
Required funds or available equity vary by documentation path, occupancy, property, and complete borrower profile.
Credit Profile
Credit requirements vary by program and complete borrower profile.
Occupancy
Available occupancy types depend on the selected financing path.
Property Types
Eligible property types depend on the selected program, occupancy, and transaction.
Documentation Path
Income, assets, or property cash flow must be documented under the selected program requirements.
Reserves and Program Features
Reserve expectations and available features depend on the selected program and complete scenario.
Program guidelines, rates, terms, loan limits, credit requirements, and availability can change. This information is educational and is not a commitment to lend or a guarantee of approval.
It is a mortgage that does not meet the qualified-mortgage definition and may use alternative underwriting or documentation.
Self-employed borrowers, investors, borrowers with complex income, or others whose profile does not fit traditional documentation may benefit.
It is an alternative-documentation option that may analyze eligible deposits over a defined period to estimate qualifying income.
Debt-service coverage ratio financing evaluates eligible investment-property cash flow relative to the proposed debt payment.
Potentially. Bank statements, a qualifying profit-and-loss statement, 1099s, or assets may be considered under available programs.
Yes, many Non-QM options are designed for eligible investment-property scenarios.
They can be. Pricing reflects the documentation, property, credit, leverage, and specific lender program.